Make lenders compete for your company.Save on time and costs.
Debt advisory for companies with $10M to $100M+ in revenue. Software builds the lender package in a day, a senior banker runs the process, and you don't pay for the analyst hours.
- 1 day
- to build the package once the documents are in. At least 7 by hand.
- 1,800+
- lenders in the book for every debt placement, screened by fit.
- Senior banker
- on every deal, from the first call to the close.
Are you a lender? Join our lender network Broker or advisor? Refer a client
An example of how a file comes together: an owner describes the business and what they need; BRUNO reads the documents, explains what lenders will focus on, shortlists lenders from the book, and drafts an anonymous teaser that goes nowhere until the owner approves it. The businesses shown are invented.
Illustrative figures and lender types. Not an offer.
Some of the 1,800+ lenders in our book
JPMorgan Chase
Wells Fargo
Bank of America
PNC
U.S. Bank
Truist
Capital One
Huntington
Regions
BMO
Comerica
Citizens
First Citizens
Zions Bank
Webster Bank
Western Alliance
First Horizon
Synovus
Umpqua Bank
Customers Bank
Newtek
Hanmi Bank
Pathward (Crestmark)
SLR Credit Solutions
eCapital
Names and logos belong to their owners and identify lenders in our database. Being listed is not an endorsement of Midas Partners, no lender pays to appear, and which lenders see your file is your decision.
You pay for the banker. Not the analyst floor.
Most of an advisory fee pays for people you never meet: analysts building the model, the lender presentation and the lender list by hand, over weeks. Our software does that work in a day, and a senior banker checks every page.
We don’t carry those analyst hours, so your fee doesn’t either.
See the documents we build- Financial modelAnalysts, by handBuilt by software, checked by a banker
- Lender presentationAnalysts, over weeksDrafted from the model in a day
- Blind teaserAnalystsBuilt from the same model, checked for anything that names you
- Lender listAnalysts and a banker's contactsScreened against 1,800+ lenders
- Lender diligence questionsAnalysts, by emailTracked in your portal, answered once
- Strategy, negotiation and closeSenior bankerSenior banker
1 day to build the package once the documents are in; at least 7 days by hand. Lender and buyer decisions, diligence and closing keep their own timelines.
Debt for what the business needs next. One banker from start to close.
Refinancing and recapitalizations
For companies replacing expensive or restrictive debt, or returning capital to owners.
The whole capital structure rebuilt around what the business earns: fewer lenders, longer terms, covenants it can live with, and a dividend or buyout where the numbers carry it.
- Financing model
- Lender presentation
- Term sheets compared
- Close
Acquisition financing
For owners and independent sponsors buying a company.
The combined model, what the target really earns once the seller's adjustments are tested, and acquisition debt placed with lenders that fit the deal.
- Combined model
- Seller earnings tested
- Lender match
- Close
Growth capital
For companies funding expansion, equipment or working capital.
Senior, unitranche, asset-based and junior debt, placed from a book of 1,800+ lenders screened by product, credit box, check size, sector and geography.
- Capital plan
- Lender presentation
- Lender match
- Term sheets compared
Selling the company, or buying one?
The same bankers run sell-side and buy-side processes, with the same model and the same package behind them.
A bank’s process. Weeks faster to market.
BRUNO, our software, builds the analyst work. A senior banker reviews it, runs the process and negotiates the close. Your name stays under a codename until you approve who learns it. Who reads your file

- 01
A confidential first conversation
A banker learns the business and what the capital is for: a refinancing, an acquisition, growth or a sale. No cost, and nothing leaves the room.
- 02
The package, in a day
Once the documents are in, software builds the financing model, the lender presentation and the blind teaser. A senior banker reviews every page, and you approve it.
- 03
To market under a codename
Lenders that fit see the teaser first. Nobody learns who you are until you approve them by name.
- 04
Term sheets side by side
Rate, fees, amortization, covenants and structure, compared line by line, with your banker's recommendation.
- 05
Diligence and close
Questions come through your portal and are answered once. Your banker negotiates the documents to close.
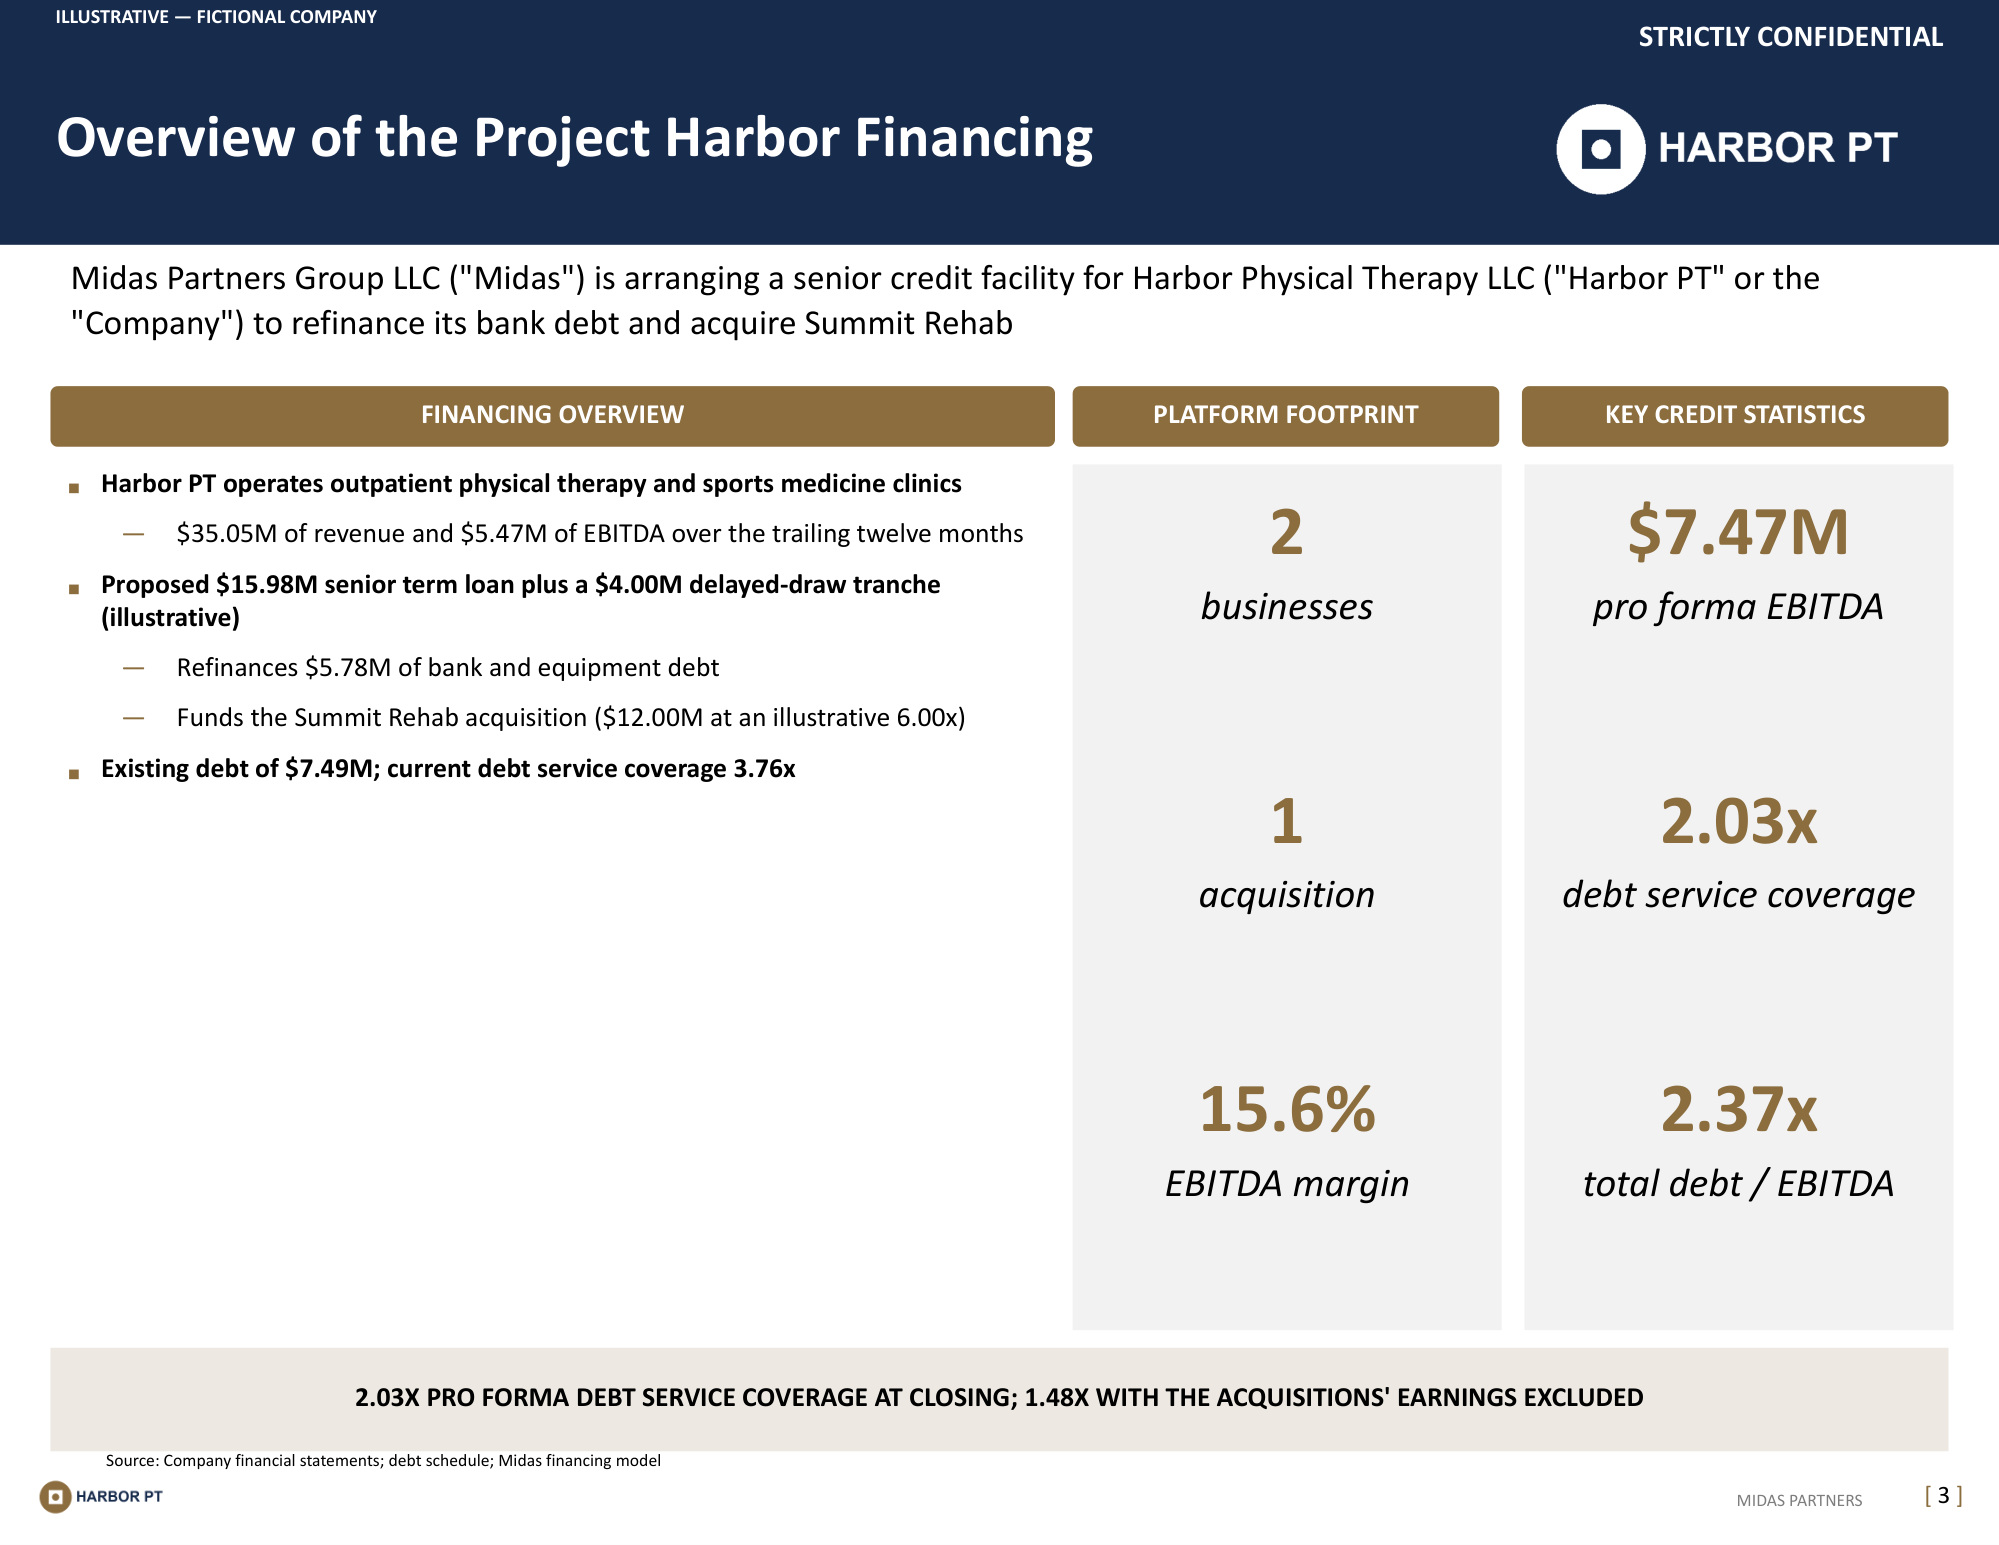
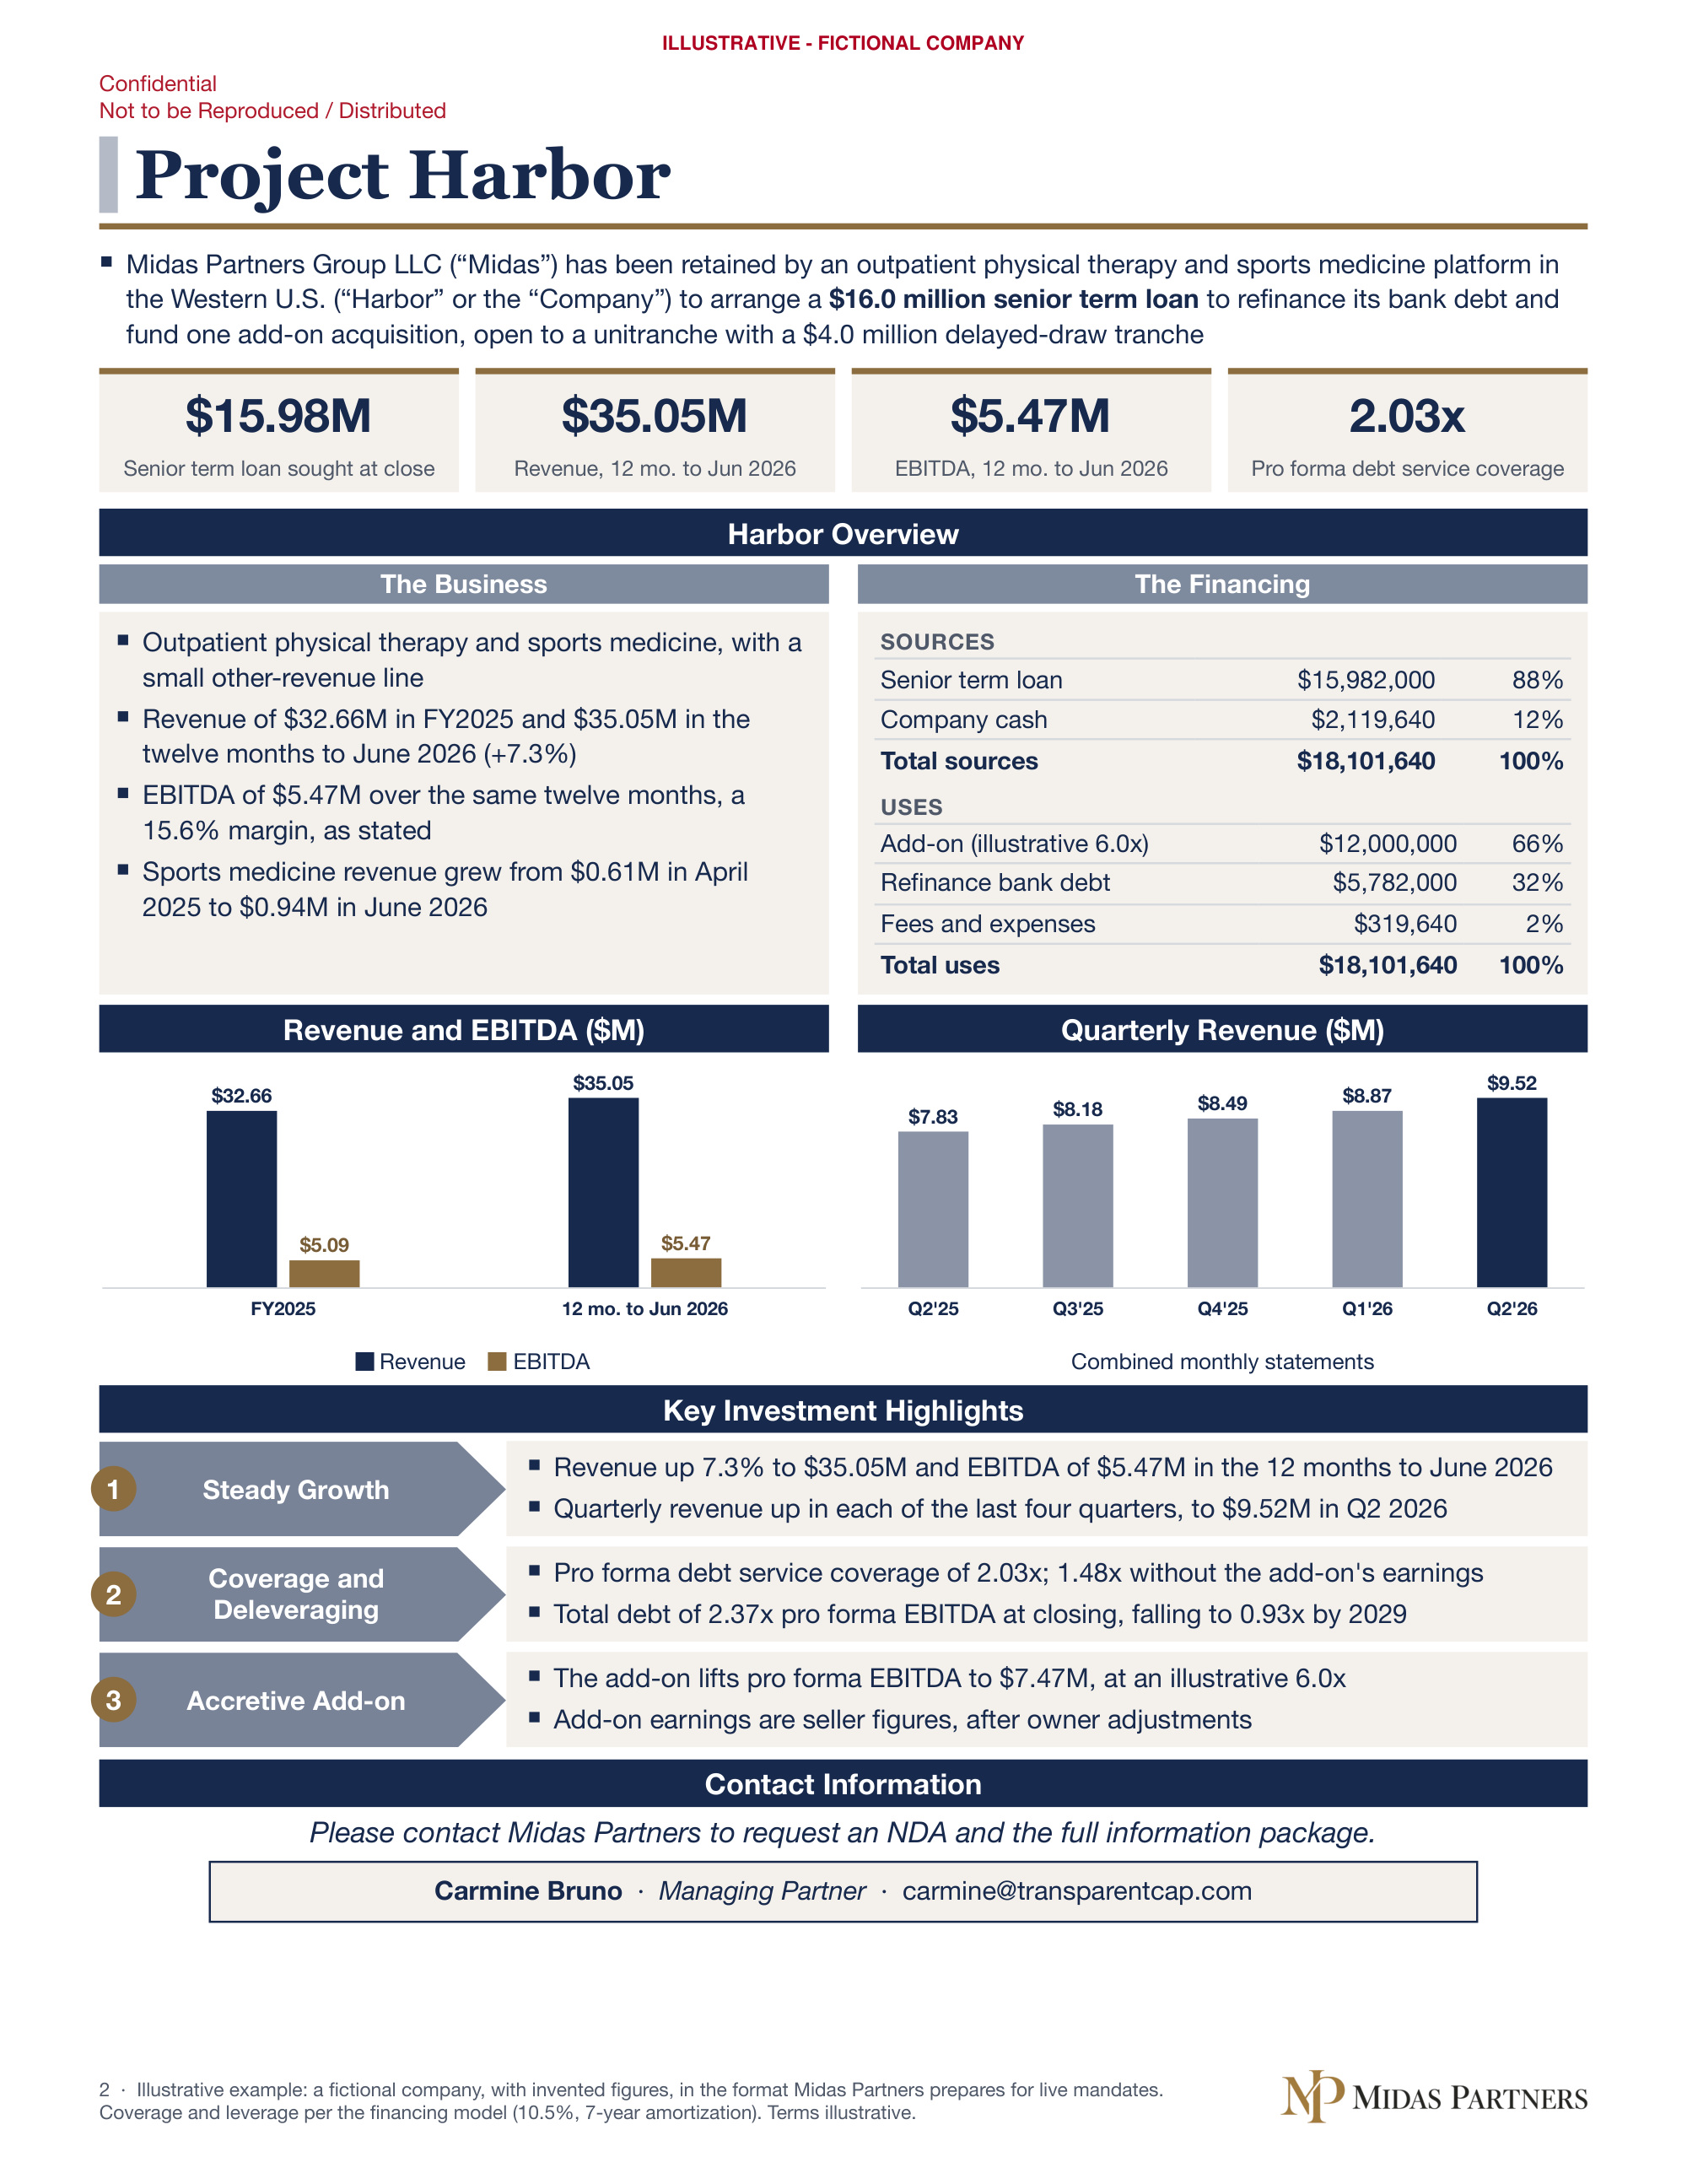
The documents a lender reads. Built in a day.
A financing model with live formulas, a lender presentation drawn from it, a blind teaser and a written recommendation. Every figure ties to the model, and a senior banker reads every page before anyone else does.
Open the full example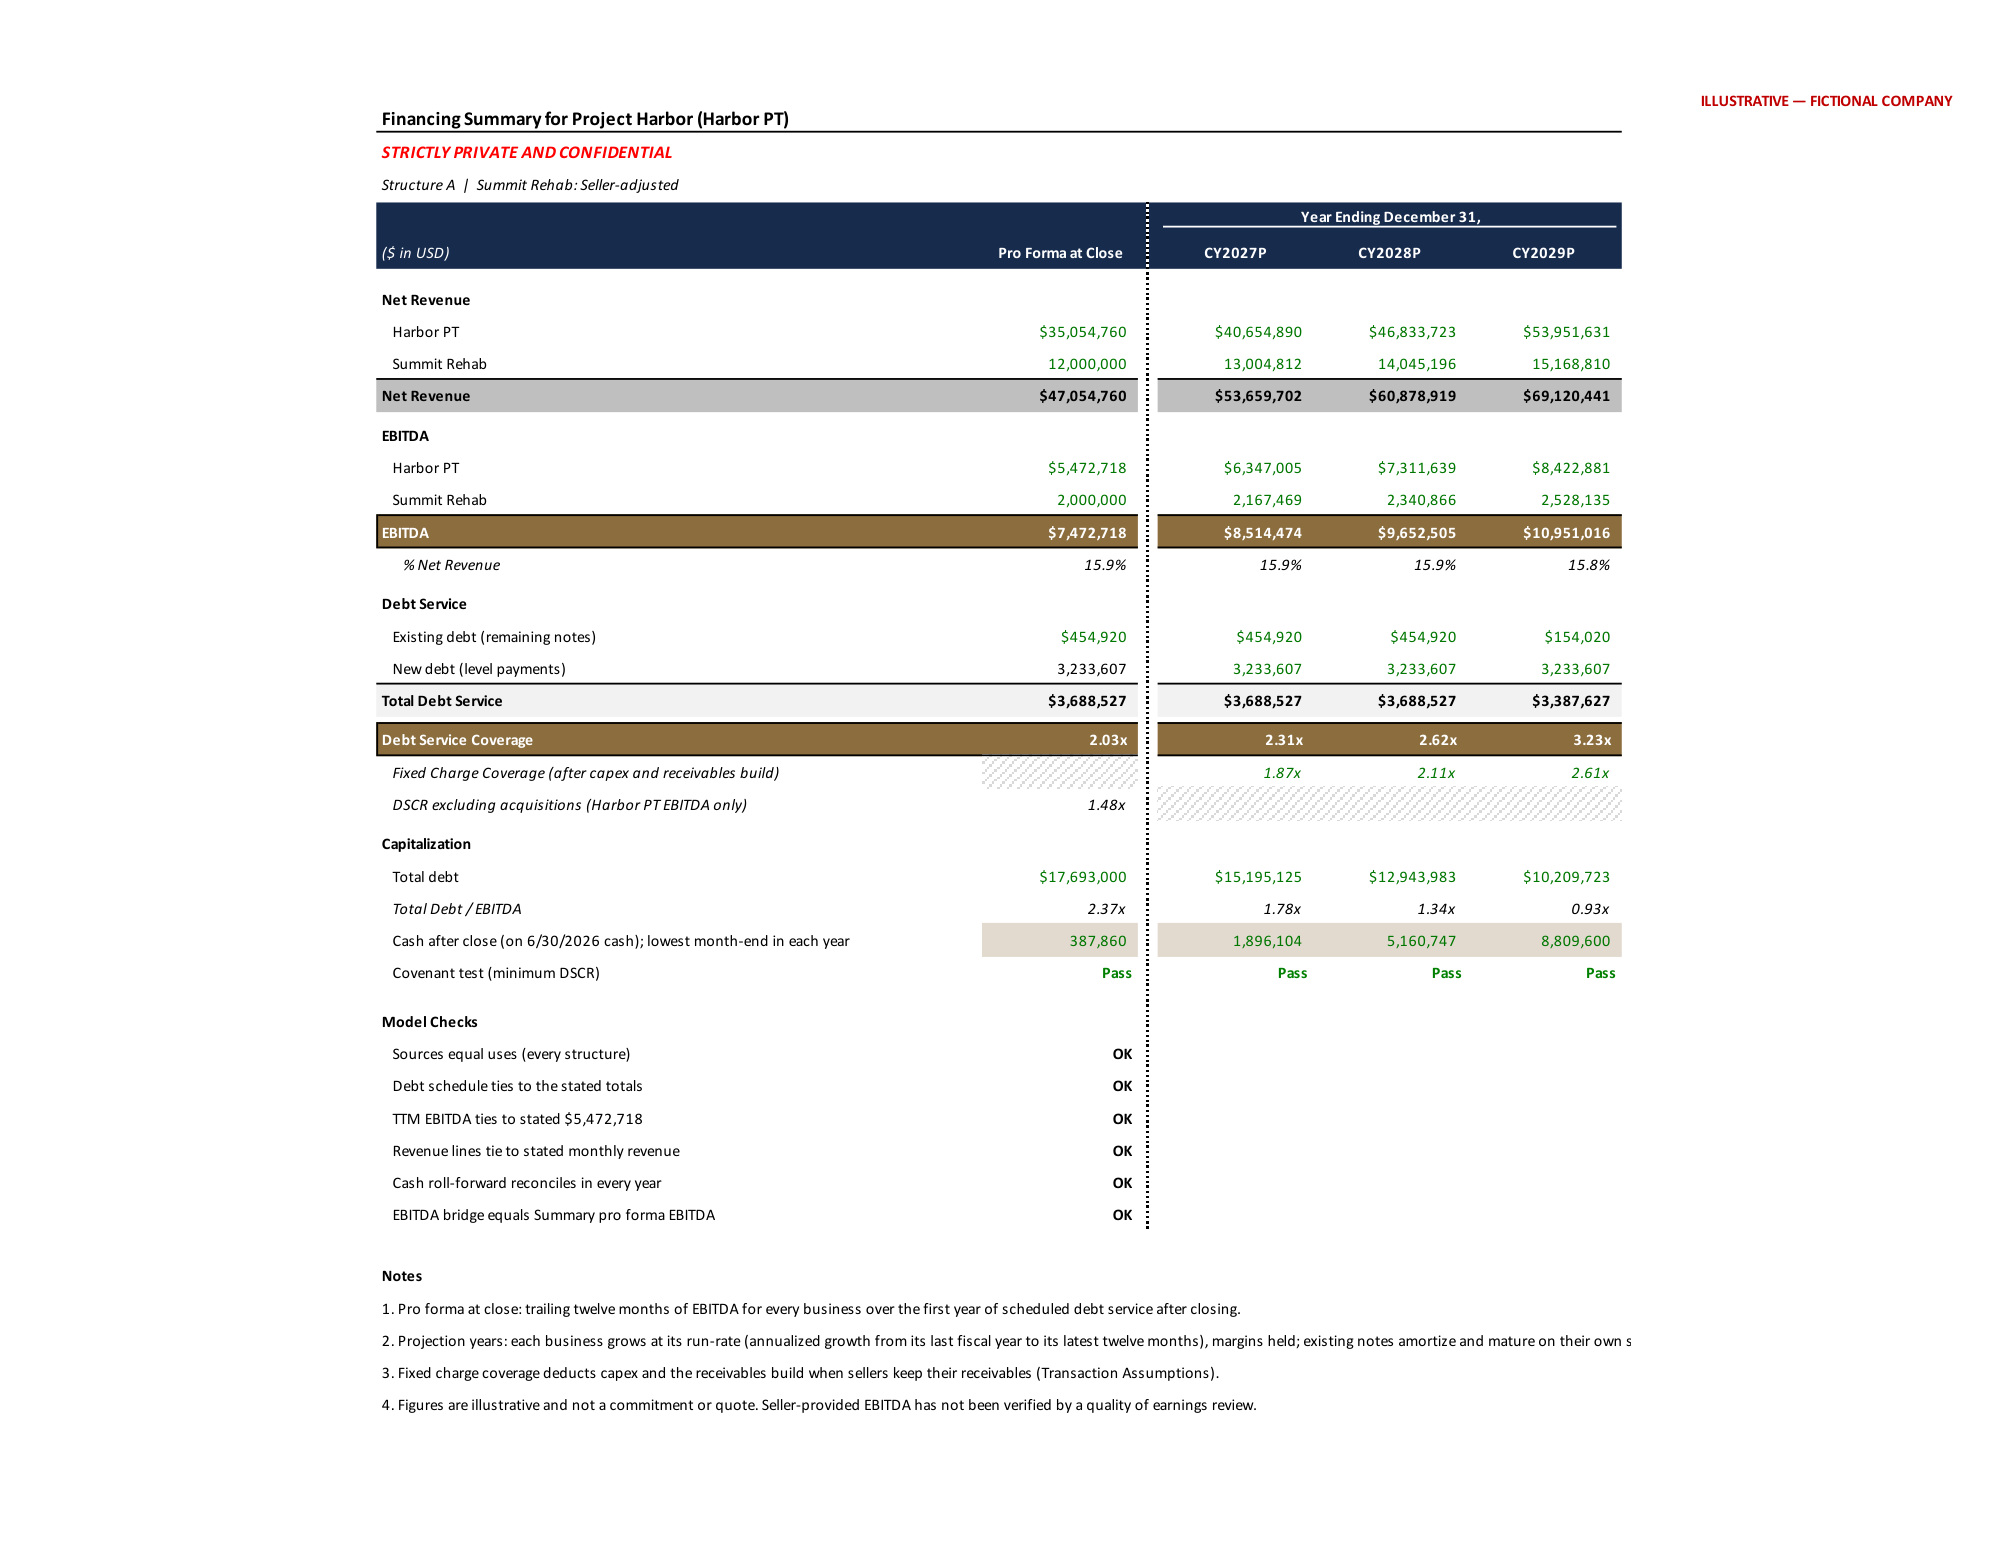
1,800+ lenders is not the advantage. Knowing which ones fit is.
The lender book is kept by product, credit box, check size, sector and geography. BRUNO screens the full book, a senior banker reviews the shortlist, and you approve every lender that asks to see who you are. Carmine learned capital structure from the wrong end of it: restructuring, where leverage, amortization, covenants and lender mismatch become impossible to ignore. Your company is routed against the book, not blasted at it.
1,366 lenders counted above, each where it has lent in that product or says it does with a source. A lender that writes more than one appears under each, so the five overlap. Counted September 23, 2026. Lenders: join the book